
Tax Incentives in Panama 2026: New Exemptions of Up to 15 Years for Tourism Investors
- Aggressive Exemptions: Up to 15 years of exemption on Income Tax (ISR) and real estate in the Caribbean, and 10 years inland.
- No More Loopholes: The new regulation replaces Law 80 and expressly prohibits duplicating benefits or subsidizing purely real estate developments.
- Guaranteed Agility: A single window coordinated by the ATP is implemented to accelerate environmental and construction permits.
The landscape for foreign investment in Central America is being reshaped under strict parameters of transparency and efficiency. The Cabinet Council has approved an ambitious tourism promotion bill designed to replace the old Law 80 of 2012, which expired on December 31, 2025.
Are you looking to make your assets profitable with complete legal security in the region? The new legislation redefines the rules of tax incentives in Panama, prioritizing capital decentralization and the modernization of critical infrastructure outside the capital district.
This update is key if you are considering starting a company in Panama. The authorities seek to avoid market distortions and channel private capital towards developments that truly boost the local economy.
The 5 Key Areas of the New Tourism Promotion
The regulatory framework opens substantial opportunities for various business models. Eligibility is not limited to mass hospitality; the approach is asymmetrical and rewards innovation:
- Development of new tourist accommodations in regions with a high investment gap.
- Modernization and comprehensive renovation of existing hotel facilities.
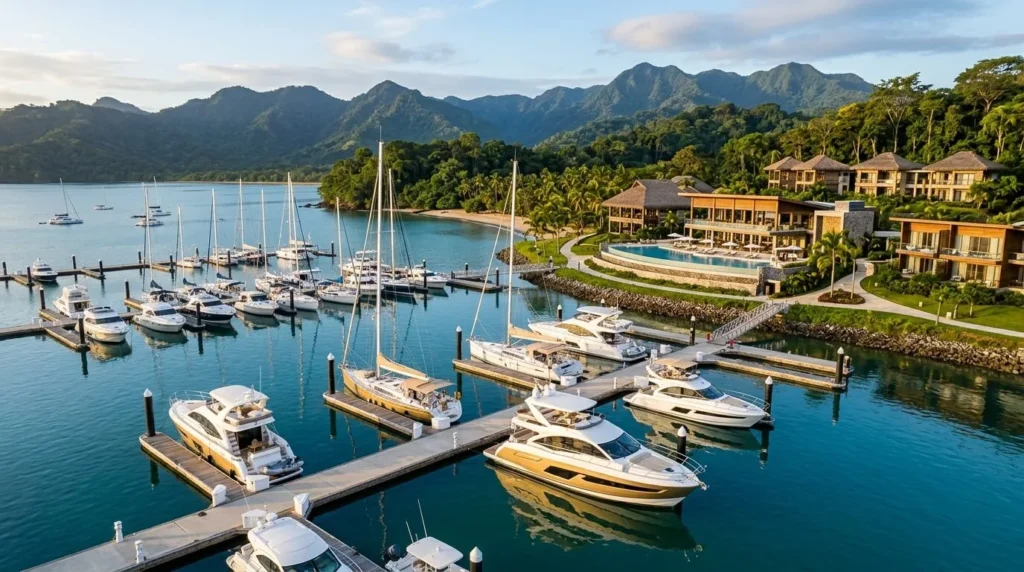
- Investments in nautical tourism, sports marinas, and service docks.
- Creation of cultural, scientific experiences, interactive museums, and technology applied to tourism.
Geography of the Incentive: Caribbean vs. Inland
The new law establishes explicit territorial differentiation. The objective is to direct resources to areas where infrastructure is more costly to implement due to transportation logistics.
| Tax Benefit | Panamanian Caribbean Region | Outside Panama District |
|---|---|---|
| Income Tax Exemption | 15 years | 10 years |
| Real Estate Tax Exemption | 15 years | 10 years |
| Importation of Construction Materials | Exempt for 5 years | Exempt for 3 years |
| Importation of Equipment | Exempt for 10 years | Exempt for 5 years |
What does this mean for your business plan? The Panamanian Caribbean is consolidating as a destination of very high long-term fiscal profitability for luxury hospitality and nautical tourism projects.
Rigorous Controls Against Real Estate Simulation
The abuse of previous regulations to finance purely residential developments under the guise of tourism projects comes to an end. Authorities have tightened inspection requirements.
The administrator of the Panama Tourism Authority (ATP) has emphasized the implementation of a compliance bond and cross-audits with the Ministry of Economy and Finance to track the traceability of all exempted assets.
Any indication that the incentives are diverted to strictly residential projects will result in the loss of benefits and severe penalties.
PanamaWay’s Analysis: How Does This Affect Your Relocation and Investment?
The 2026 framework demands impeccable legal and fiscal structuring from the initial draft. The introduction of the single window promises to reduce traditional Panamanian state bureaucracy, but rigor in fiscal substance controls is non-negotiable.
If your intention is to relocate and invest smartly, combining these incentives with obtaining your tax residency requires a multidisciplinary approach.
A practical scenario resolved by our team:
Earlier this year, a European wealth group contacted us to develop a boutique complex of ecological cabins and a small marina in Bocas del Toro. Initially, their financial plan blended the sale of residential vacation units with the hotel’s operation under the same limited company.
Under current guidelines, the ATP would have immediately rejected the application due to suspected real estate fraud. Our team of senior consultants immediately restructured the corporate architecture: we segregated the land from the commercial operation, created a Limited Company exclusively dedicated to tourism exploitation, and designed a transparent accounting traceability system. Thanks to this, the project was successfully pre-qualified to receive the full 15-year ISR exemption in the Caribbean, protecting the partners’ assets against tax contingencies.
Don’t take unnecessary risks due to lack of specialized local advice. The difference between obtaining a massive tax exemption or facing a tax inspection lies in planning.
If you wish to structure your assets with full guarantees in this new legal scenario, let’s analyze your relocation case without obligation and define the best strategy for your company.